
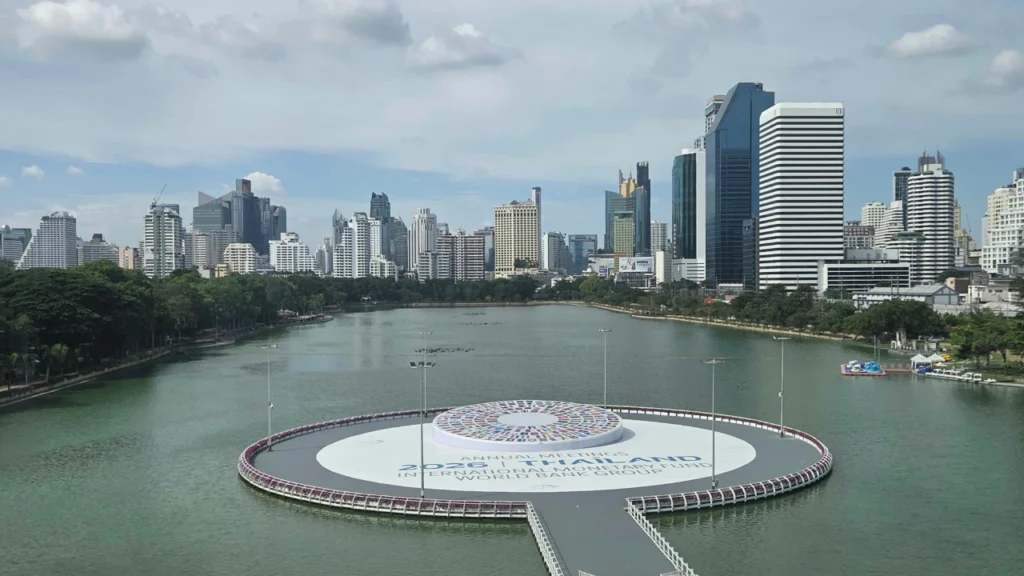
The world’s finance ministers arrived in Bangkok 2026 meetings facing a familiar arithmetic problem. Public expenditure continues to grow, borrowing has become more expensive, and the capacity of many governments to absorb further economic shocks is diminishing. The 2026 IMF and World Bank Annual Meetings, held from October 12 to 18, offered a frank assessment of the fiscal challenges ahead.
Much of the international attention fell on artificial intelligence, geopolitical uncertainty and the future of development finance. Nevertheless, the discussions also exposed a more immediate concern for ministries of finance: how to make existing public resources work harder and strengthen the institutions responsible for raising them.
For Data Tech International (DTI), the conclusions from Bangkok reinforce a practical argument about domestic revenue mobilization. Improving the collection of taxes already established in law is among the most accessible sources of additional fiscal capacity. Digital reform can accelerate that process, provided governments choose proven technology, develop local expertise and concentrate their efforts on the administrative changes that produce measurable results.
5 Takeaways from IMF/WB Meetings in Bangkok 2026
- Fiscal buffers are running out, so governments must enhance revenues rather than rely on more borrowing or higher tax rates, improving the efficiency of existing tax systems is the most accessible route.
- Building complex fiscalization technology from scratch carries hidden, long-term costs (security, maintenance, staff, legislative updates). Proven commercial off-the-shelf systems like TaxCore reduce implementation risk and speed up compliance gains.
- Better tax administration starts with reliable transaction records, consistent reporting, and effective verification, these make VAT administration more efficient and enable risk-based enforcement.
- Capacity building is not optional. Technology investments only pay off when tax officers and local technical teams are trained to operate systems, interpret data, and support taxpayers.
- Institutional capacity creates fiscal capacity. The most important measure of digital tax reform is whether it strengthens a government’s ability to collect revenue already due under the law, and sooner reliable reporting becomes operational, the faster compliance improves.
Bangkok’s Fiscal Warning: Governments Are Running Out of Room
On October 14, IMF Managing Director Kristalina Georgieva warned that the global economy’s resilience was reaching its limits. Speaking at the Global Policy Agenda press briefing, she described the depletion of fiscal and energy buffers as governments confronted persistent inflation and successive economic shocks.
Her message to policymakers was, as always, very direct: “Now is the time to enhance revenues.” The urgency reflected an increasingly difficult fiscal environment. Debt-service obligations are absorbing resources that could otherwise finance infrastructure, education, healthcare and economic development. For lower-income countries, the consequences are especially severe.
The implications for revenue authorities are considerable too. Governments cannot rely indefinitely on additional borrowing, external assistance or higher tax rates to meet their obligations. Improving the efficiency of existing tax systems offers another route. Stronger compliance, more complete reporting and reliable evidence of taxable economic activity can contribute to sustainable revenue growth while supporting fairer competition.
The WB Bangkok 2026 Message: Make Scarce Resources Go Further
2026 Bangkok Annual Meetings plenary brought an equally relevant perspective from World Bank President Ajay Banga. His address examined how governments and development institutions could increase the impact of limited resources while supporting employment, investment and economic growth.
Banga pointed to reforms within the World Bank itself, including a reduction in project preparation time from 19 months to nine. He also stressed the importance of physical and human infrastructure, regulatory certainty and institutional capacity. According to his official plenary remarks, 30% of the institution’s public-sector financing during the previous year supported policy and institutional reform.
For DTI, this emphasis on efficiency and execution has direct relevance to national fiscalization programmes. Public administrations routinely face decisions about whether to develop technology internally or acquire established solutions. Project duration, implementation risk and institutional readiness deserve the same attention as acquisition costs. Every additional year spent developing a system delays the potential compliance improvements that justified the investment.
Better Taxation Begins with Better Administration
The fiscal argument gained further substance when Rodrigo Valdés, Director of the IMF’s Fiscal Affairs Department, addressed the Fiscal Monitor press briefing in Bangkok.
“Fiscal risks are rising and action is needed in many countries,” he told reporters. His recommendations included improving tax systems, strengthening fiscal institutions and adopting better-designed policies capable of supporting economic activity while safeguarding public revenue.
The IMF’s October 2026 Fiscal Monitor: Taxing Better to Boost Growth develops this argument through research on tax neutrality, administrative efficiency and compliance costs. For indirect taxation, the implications reach into the everyday operations of revenue authorities. Reliable transaction records, consistent reporting requirements and effective verification can make VAT administration more efficient. These improvements also provide a stronger foundation for risk-based enforcement.
The Overlooked Cost of Building Technology from Scratch
National tax administrations have legitimate reasons to exercise control over their digital infrastructure. Nevertheless, creating complex fiscalization technology internally requires substantial financial resources, specialist personnel and sustained institutional commitment. Software development represents only one part of the obligation.
Governments must also finance security, testing, integrations, maintenance, documentation and continuous adaptation to legislative changes. Public-sector development teams face competition for experienced specialists, while changes in leadership and budget priorities can affect project continuity. The accumulated costs may extend far beyond initial estimates.
This issue predates Bangkok. The IMF’s technical guidance on commercial off-the-shelf systems describes the organizational demands of introducing established software into tax administrations. Its lessons support careful consideration of COTS for tax administration, including governance, migration, testing and business-process reform. The guidance concerns core tax systems, although many implementation principles also apply to fiscalization. DTI’s conclusion is that governments should reserve bespoke development for requirements that genuinely demand it.
TaxCore – a Practical Example of COTS Fiscalization
DTI’s TaxCore platform was developed to support the certification, monitoring and verification of fiscal transactions. Its established architecture combines secure invoice records, digital signatures and reporting mechanisms with administrative tools for supervision and compliance analysis. National implementations demonstrate how common technology can operate within different regulatory environments. In Fiji, the VAT Monitoring System uses TaxCore to support fiscal reporting. In September 2025, the Fiji Revenue and Customs Service, working with DTI, introduced a public monitoring dashboard providing information on fiscalized taxpayers, transactions, invoice volumes and receipt verification. The initiative also enables citizens to report suspected irregularities.
These functions illustrate a broader approach to domestic revenue mobilisation. Better information allows administrations to direct enforcement resources more effectively and gives compliant businesses greater protection against unfair competition. TaxCore provides the technological foundation for these activities, while national authorities determine the rules, implementation priorities and enforcement measures.
Capacity Building Determines Whether Reform Endures
Bangkok’s emphasis on human capital carries an important lesson for digital government. During the October 16 plenary, Banga observed that “Skills are part of the package.” Technology investments require trained people who can operate systems, manage information and apply the results to practical decisions.
For DTI, capacity building is integral to fiscalization reform. Tax officers need to interpret transaction records, investigate irregularities and support taxpayers. Local technical teams must understand the platform’s operational requirements, integrations and continuity procedures. Sustainable reform depends on institutions that can perform these responsibilities confidently.
A recent example comes from Eswatini. In September 2026, DTI conducted a two-week TaxCore training programme for Eswatini Revenue Service personnel in Belgrade. Participants completed practical exercises covering enrolment, secure-element management, inspection, accreditation and reporting. The programme equipped local staff for responsibilities associated with the national rollout, illustrating how implementation expertise can be transferred to the administration that will ultimately operate the system.
Bangkok 2026: Institutional Capacity Creates Fiscal Capacity
The 2026 Bangkok Annual Meetings offered a clear warning about the condition of public finances. Countries must manage growing demands on their budgets while improving economic resilience and creating opportunities for development. Domestic revenue mobilization will remain central to that task.
Summit’s message was that public resources must deliver more. For revenue authorities and ministries of finance, the opportunity begins with making better use of what they already have: established tax legislation, capable public institutions, and proven technology that can help them fulfil their responsibilities.
The most important measure of a digital tax reform is its contribution to public administration. A system must provide reliable evidence, enable effective enforcement, support taxpayers and strengthen the government’s ability to collect revenue already due under the law. Sooner reliable reporting becomes operational, faster will governments begin turning better compliance into stronger, more sustainable national finances.